All Categories
Featured
Direct Consumer Advice for Life Insurance Selection
Understanding 2026 Medicare Benefit Options for Seniors
Selecting the Best 2026 Medicare Supplement Coverage

Understanding 2026 Medicare Benefit Options for Seniors
Table of Contents
However, knowing the distinctions in between specific health plans, like an HMO and a PPO strategy, is required to secure the ideal health protection for you, your household, or your employees. In this blog site post, we'll walk you through the crucial differences in between HMO and PPO strategies, examine their benefits and drawbacks, and show you how each strategy works with a health reimbursement plan (HRA).
Because of this, these policies provide lower premiums and out-of-pocket costs. PPO plans provide more flexibility in choosing health service providers and services than HMO plans. But, they frequently have higher premiums and deductibles, and need policyholders to file their own claims for out-of-network care, which can be complicated and time-consuming.
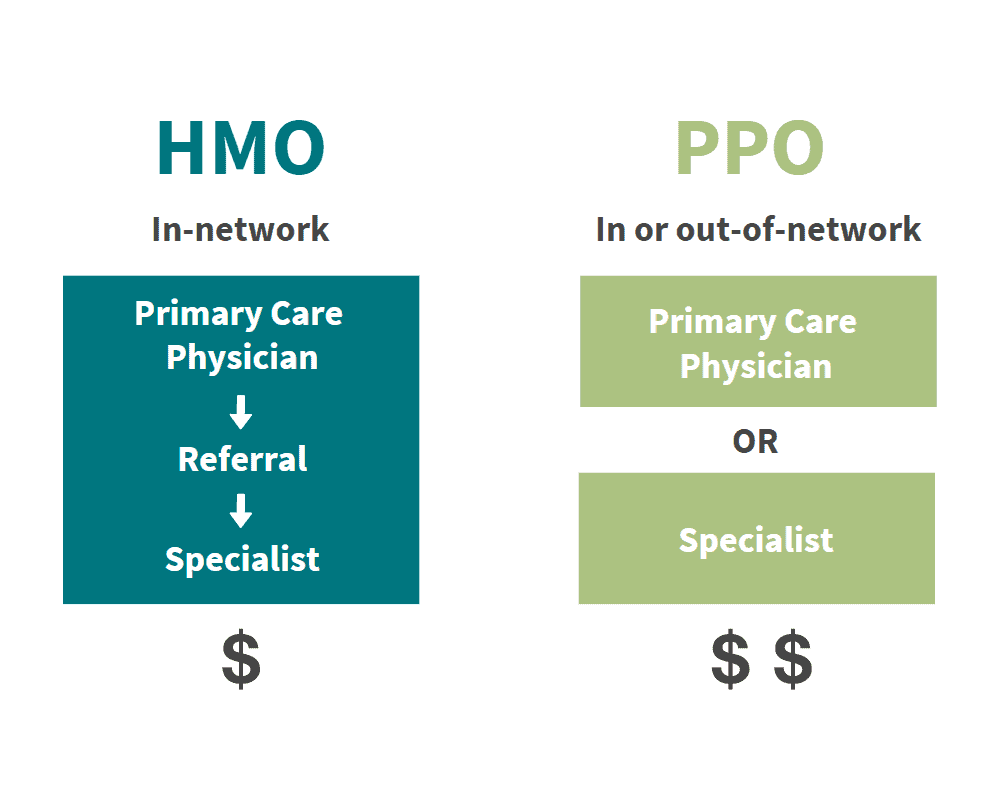
An HMO is a kind of health strategy where a group of network doctors, medical facilities, and other medical care service providers contract with an insurance coverage company to use insurance policy holders various covered services and items in exchange for a premium. Service providers within the HMO network concur to provide care to insurance policy holders at a lowered rate.
In 2023, 13% of staff members in the U.S. with medical insurance coverage enrolled in an HMO plan1. Because these policies typically have lower premiums and out-of-pocket expenses compared to other kinds of health strategies, they can look like an attractive alternative for those trying to find coverage. The lower general expenses come with certain limitations.
Reviewing 2026 Medicare Advantage Policies
Their HMO likewise will not cover the expenses of out-of-network care or treatment from a professional that happened without a PCP recommendation, except if a policyholder needs emergency care. Before identifying if an HMO suits you or your organization, you need to examine the benefits and drawbacks. HMO plans normally have low premiums and copayments.
Your strategy will also generally cover in-network professional care with just a little copay for services. When you enlist in an HMO plan, you have to pick a PCP who will be your main point individual to reach out to when you need care. In return, they collaborate your care, manage your overall treatment, and make recommendations for professionals.
Additionally, your PCP serves as your medical supporter, and you might develop a strong bond with them, leading to you getting much better and more constant care. While these benefits of HMO strategies may seem attracting, there are prospective disadvantages that you should think about before enrolling. If you desire your HMO to cover the cost of your care, you must get care from a particular network of service providers in your area.
If you see a non-network company, you'll be accountable for your entire bill without the assistance of your insurance company. If you require to check out a specialist for treatment, you must ask your PCP for a referral for an in-network professional in advance. If your PCP doesn't refer you, you should pay the entire expense of the expense alone, which can be costly.
Nevertheless, your policy will lay out the scenarios that it thinks about an emergency. If your emergency situation doesn't fit the criteria in your strategy, you'll need to foot the bill on your own. In 2023, the typical annual premium for a group HMO strategy was $8,203 for self-only protection and $23,758 for family coverage2.
Securing Burial Insurance to Support Seniors
For household coverage, employers contributed $16,600, and staff members contributed $7,158. Like other kinds of health insurance, HMO policies might have an annual deductible. A deductible is the set amount of money a plan participant need to pay out-of-pocket before their insurer begins to cover their medical care expenses. In 2023, the average deductible for an HMO strategy was $1,200.
KFF found that 33% of people enrolled in a self-only HMO do not have a deductible3. (ACA) Market strategy was $9,100 for self-only protection and $18,200 for household coverage4.
A PPO policy is a kind of health plan in which an insurance coverage provider agreements with medical professionals, healthcare professionals, and medical centers to produce a list of "favored" health care companies for policyholders. When individuals with a PPO strategy get healthcare from an in-network provider, their health insurance provider pays the service provider at an agreed-upon reduced rate.
PPOs are the most typical plan that employers offer. In 2023, 47% of people with a group health insurance coverage strategy have a PPO2. These strategies are popular since they don't require members to pick a PCP before enrolling and allow members to pick from a larger variety of in-network companies than they can with an HMO strategy.
PPO plans offer several advantages that make getting medical care a convenient and favorable experience. PPO strategies have a broad network of companies offering the same types of medical services with set similar rates.

Latest Posts
Direct Consumer Advice for Life Insurance Selection
Understanding 2026 Medicare Benefit Options for Seniors

Selecting the Best 2026 Medicare Supplement Coverage